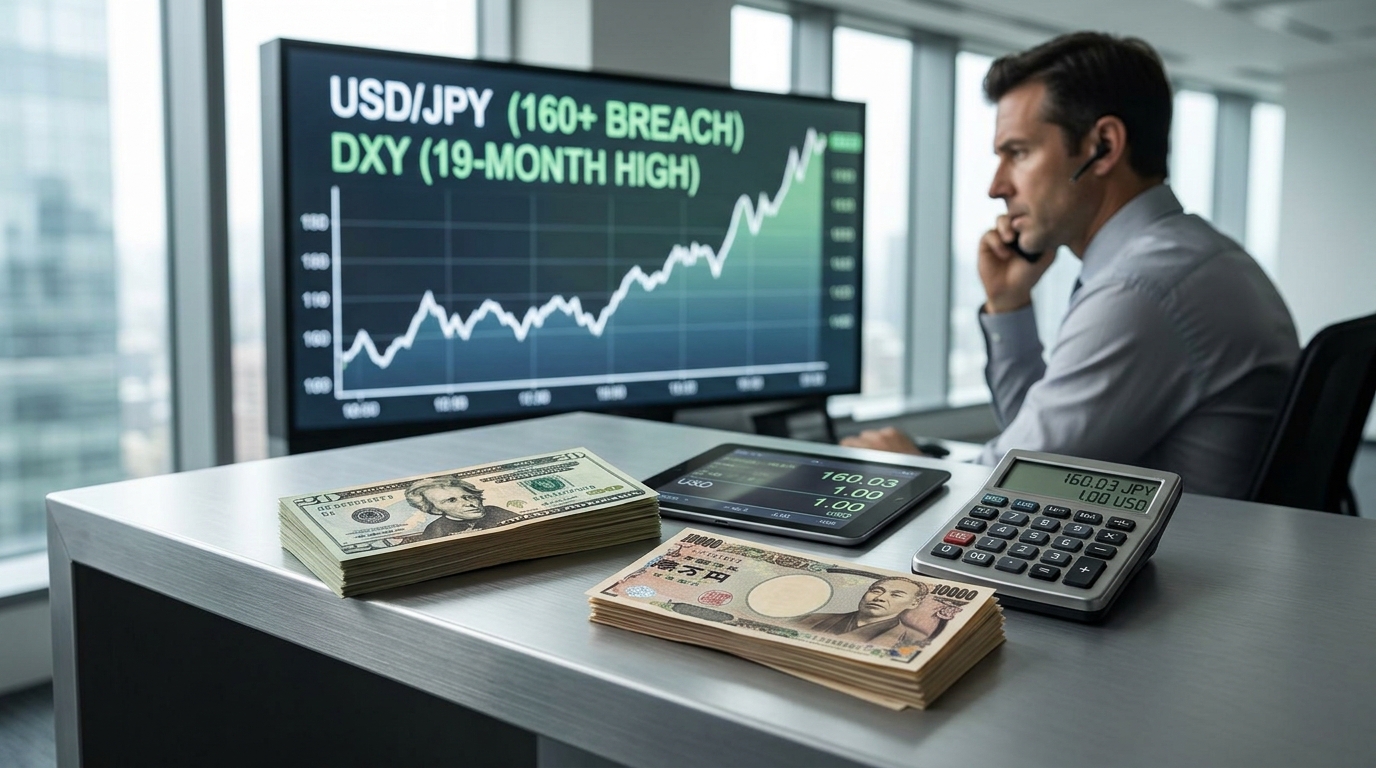
The yen weakened past 160 per US dollar on Friday, November 13, crossing the 160 threshold for the first time since early September. That is not a near-miss or a retest. It is a confirmed breach, the third consecutive session of yen weakness, and it arrived with the dollar index already at its highest level since April 2025.
The US Dollar Index is holding near a 19-month high around 103, boosted by hawkish Fed rhetoric and hotter-than-expected US CPI data. The underlying arithmetic is straightforward: the dollar’s recent rise has been driven by growing expectations that the Federal Reserve will raise its key interest rate in December following stronger-than-expected US consumer inflation data, a move that could further widen the interest rate gap between Japan and the United States.
With the federal funds target range at 3.75% to 4.00%, markets are increasingly pricing a 25bp hike at the mid-December meeting, which would lift the target to 4.00% to 4.25%. Any upside surprise in Friday’s producer price data would sharpen that debate fast.
The dollar-yen trade is the currency expression of this rate story, and right now it is the cleanest version of it. The 10-year Treasury yield has been pushing higher again in recent sessions. For the yen to strengthen, the Bank of Japan would need to tighten policy more quickly. Until that happens, the wide yield spread is driving the US dollar higher, leaving the yen as a funding currency in carry trades. Bank of Japan communications this week have underscored that policymakers are still weighing how quickly to proceed, and that the pace of further tightening is not yet settled.
That internal BoJ paralysis is the fundamental tailwind for dollar-yen bulls. But 160 is where the trade gets complicated, and that is precisely the point.
Finance Minister Satsuki Katayama told reporters Friday that officials were monitoring sharp, one-sided moves in the foreign exchange market and said Japan would respond appropriately, including in close coordination with the United States.
This is not boilerplate. Japanese finance ministry language on “one-sided” and “rapid” FX moves follows a well-worn escalation ladder in which verbal concern typically precedes more pointed warnings and, in past episodes, actual intervention by the Ministry of Finance through the Bank of Japan as agent. More importantly, Japan has confirmed it bought yen in coordination with the United States on July 31, the first such joint yen-buying operation since 1998. The Ministry disclosed three yen-buying operations totaling about 15.4 trillion yen, roughly $96.5 billion, across July 30, July 31, and August 3. Washington has now demonstrated it will participate. That changes the calculus for anyone running a large short-yen position through 160.
Katayama’s comments make intervention a more serious risk for anyone pushing dollar-yen above 160, especially with the market now treating coordinated action as a live possibility. Societe Generale notes support at 158.70 and resistance at 160.90. Those are your brackets.
The trade is long dollar-yen on dips toward 158.70 to 159.00, with the intervention threat at 160 acting as a ceiling that defines position sizing rather than invalidating the thesis. The underlying pressure on the yen remains, as rising Fed hike expectations keep rate differentials in the dollar’s favor. A confirmed December hike, or any hawkish surprise from today’s PPI reading, extends that pressure. The stop is a sustained reversal below 158.50, the zone that preceded this week’s breakout. Above 160.90, the next meaningful resistance is open air toward 162, but only if Tokyo stays quiet, which is the risk every dollar-yen bull is now paid to manage.