Mitsubishi UFJ Financial Group reported its first-half results this morning, and the numbers are hard to argue with. MUFG posted record first-half net profit of ¥1.63 trillion for the six months ended September 30, 2026, up 26% year over year, marking the bank’s fourth consecutive record first-half profit, with net operating profit also rising 26% to ¥1.62 trillion on stronger lending, deposit, and fee income. That is roughly $10.4 billion in six months from a single bank. The question for a US-listed investor is whether that number is as good as it looks once the currency is factored in.
What Is Driving the Results
Lower credit costs, stronger fees, wider lending spreads, and support from Morgan Stanley drove the half. Credit costs declined ¥65.7 billion year on year, helped by reversals after the sale of large overseas provisions and several reversals in Japan. The lending side benefited directly from the BOJ’s rate cycle. Net interest income rose 29% to ¥1.85 trillion, helped by higher Japanese interest rates, which added about ¥140 billion to net operating profit, and by loan growth at home and abroad. Fee income rose 14% to ¥1.23 trillion.
The Morgan Stanley connection keeps paying. Equity-method earnings increased sharply, mainly because of Morgan Stanley’s strong results, and that contribution was a major factor behind MUFG’s ¥150 billion upward revision to ordinary profit. MUFG owns roughly 24% of Morgan Stanley, and when Wall Street books a strong quarter, Tokyo benefits.
Why Wall Street Is Paying Attention
The bank raised its full-year net profit forecast to ¥2.8 trillion from ¥2.7 trillion and announced a share buyback of up to ¥200 billion. It also raised its annual dividend forecast to 100 yen a share. For a bank that was earning almost nothing on domestic loans three years ago, that combination of raised guidance, buyback, and dividend growth is a material shift in capital return posture.
The macro backdrop supports the thesis. Some 83% of economists forecast the Bank of Japan will raise borrowing costs from the current level of 1.25% at its meeting ending December 18. At the late-October meeting, Reuters reported the BOJ said underlying inflation had roughly hit its 2% target, signalling a more hawkish phase. Every 25-basis-point hike widens MUFG’s domestic lending margin. The bank quantified that benefit itself: higher Japanese rates added roughly ¥140 billion to first-half net operating profit alone.
The Currency Problem
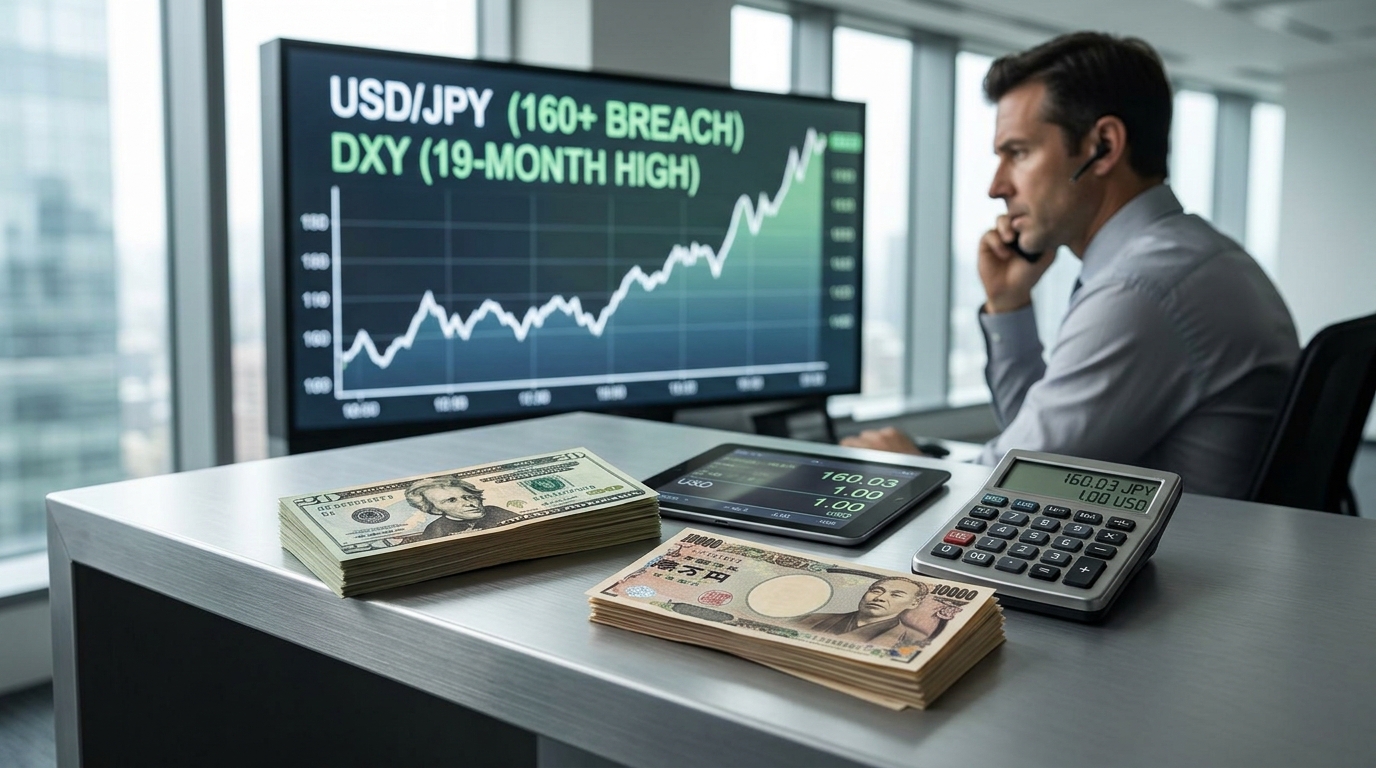
Here is the complication a US investor cannot ignore. The USD/JPY exchange rate stood around 159.95 on November 13, 2026. Treasury yields near 5% and Fed hike expectations are colliding with Japan’s record ¥15.4 trillion of currency defense from July 30 through August 26, as Reuters reported in September. Tokyo warned markets again this week, but no fresh intervention had been confirmed in official disclosures as of November 12.
Buying MUFG’s US-listed ADR at 160 means accepting yen exposure at precisely the level where Japan has intervened this year. If the BOJ delivers a December hike and the yen strengthens toward 155, US holders collect a currency gain on top of the earnings story. If the Fed keeps pressure on and the yen drifts toward 164 again, those ¥1.63 trillion in profits translate into fewer dollars. A weaker yen added about ¥35 billion to first-half results, which shows the currency tailwind is already baked into the record numbers. A reversal would work both ways.
What Could Go Wrong
MUFG’s first-half credit cost improvement was partly driven by reversals, not purely by clean portfolios. If overseas provisions re-emerge, that tailwind reverses. The Morgan Stanley contribution is real but volatile: a weaker quarter on Wall Street subtracts directly from MUFG’s equity-method line. And the BOJ hike that expands lending margins also raises the cost of Japan’s government debt, which MUFG holds in size.
Sumitomo Mitsui and Mizuho are reporting the same day, so relative positioning within the Japanese megabank sector will sharpen quickly. If peers post comparably strong numbers, MUFG’s premium to book may compress even as earnings rise.
The Bottom Line
MUFG’s fundamentals are the best they have been in decades: record profit, raised guidance, a buyback, a dividend at 100 yen, and a rate cycle that structurally favors Japanese lenders. The stock deserves serious consideration. But the investor buying MUFG in New York this morning is also buying the yen at 160, where Japan has intervened this year and where a December BOJ hike could cause a sharp reversal. That is not a reason to avoid it. It is a reason to size it honestly, knowing the currency position is as live as the banking thesis.