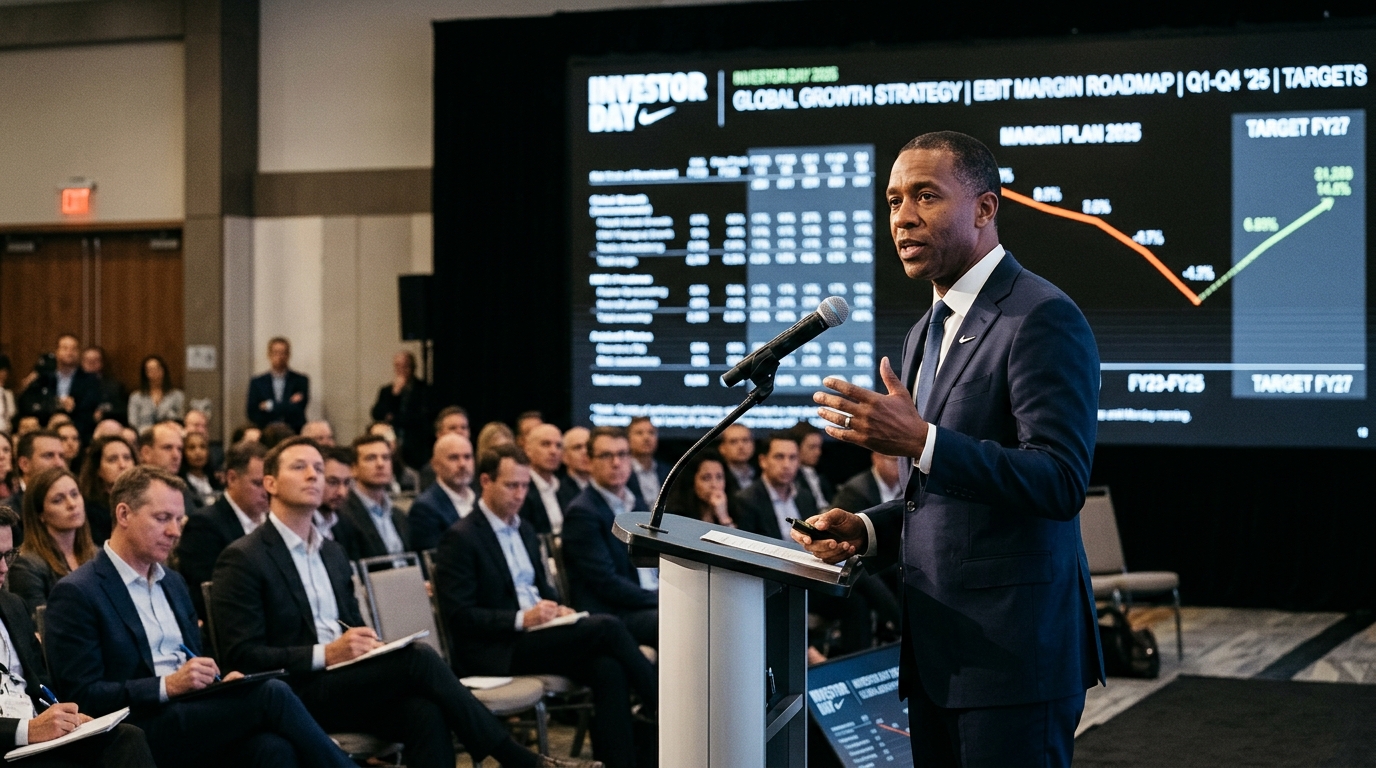
Nike arrives at its first investor day in nine years with a share price near $38 and an EBIT margin that fell from 16% at its peak to 8.2% in fiscal 2025. That gap is not a footnote. It is the entire story, and Monday is when management either closes it on paper or confirms investors’ worst fear: that the recovery is real but too slow and too vague to price.
Nike plans to host its investor day on November 16–17, 2026, with main-stage presentations webcast live on Tuesday, November 17, beginning at approximately 8:30 a.m. Pacific time. CEO Elliott Hill is expected to lay out the brand’s future plans nine years after Nike last held a formal investor day. The bar analysts have set is low. What they need to hear is specific.
The Margin Math That Has to Work
Margins are what management has to fix. Nike’s EBIT margin ran at 12.1% in fiscal 2023 and 12.7% in fiscal 2024, then fell to 8.2% in fiscal 2025. This is fundamentally a margin story, not a revenue story. In a base-case scenario, revenue grows only 1.8% a year from fiscal 2026 to fiscal 2031, while adjusted EBIT margin needs to rebuild from roughly 5.8% in fiscal 2027 to 11% in fiscal 2031.
When management lays out its five-year outlook, investors need a date for getting back to double digits. Stifel reiterated a Hold rating ahead of the event, expecting the company to outline a five-year financial framework that anticipates low-single-digit revenue growth and a low-double-digit EBIT margin, supporting projected earnings of $3 per share by fiscal 2031. That is a reasonable target. The question is whether Hill and CFO Dave Denton are willing to commit to it publicly, with a year attached.
Wholesale and Gross Margin: The Two Levers
Gross margin is where the turnaround will show up first, and the recent trajectory is uneven. First-quarter fiscal 2027 consolidated gross margin came in at 42.8%, 60 basis points higher than the prior year, helped primarily by lower warehousing and logistics costs. That is directionally right but driven by cost efficiencies, not pricing power. Lower average selling prices on the Nike brand, primarily due to higher discounts and channel mix, partially offset those gains. Discounting is still a drag, which means inventory discipline has not fully landed.
Wholesale is improving. Nike has been rebuilding its wholesale relationships, expanding outreach, and improving how it shows up across channels, with wholesale revenue up 4%, and significant investments made in refreshing more than 15,000 spaces in wholesale doors around the world. That matters because overreaching on direct-to-consumer at the expense of wholesale is what led the company to this position. The pivot back is working, but Wall Street wants to know the economics of the new channel mix and how much of the resulting margin compression is structural versus transitional.
Pace: Real Savings, Distant Payoff
CFO Dave Denton said the cost to implement Pace will be approximately $1 billion over the program’s life, in addition to approximately $300 million of severance-related costs in fiscal 2026, with the majority of savings expected to be realized in fiscal years 2029 and 2030. Pace is built around four priorities: accelerating supply chain modernization, organizing into three geographies, establishing a new campus in India, and changing the workforce.
The back-loaded savings timeline is the structural risk in the bull case. The Pace program’s roughly $2.5 billion in cumulative savings through fiscal 2031 should support margin recovery, but with the bulk of benefits arriving in fiscal 2029 to 2030, margin sustainability will depend on disciplined execution in the interim. Monday’s presentation has to show investors exactly how much of that savings reaches the profit line, and when.
Bull Case vs. Bear Case
The bull case rests on cost discipline amplifying a product-led recovery, with savings landing as the top line troughs, and fewer markdowns supporting gross margin recovery as a leaner cost base drives overhead leverage. Performance categories, including running and training, are showing real momentum under Hill’s Sport Offense initiative.
The bear case is simpler. Nike is a recovery story whose timing is hard to underwrite given a valuation that still sits at premium multiples relative to peers, with the timing and magnitude of top-line and margin recovery difficult to predict. For fiscal 2027, Nike expects revenue to decline in the high-single digits. Paying for a recovery that is at least two full fiscal years from materializing is a proposition that requires a specific, dated commitment from management, not a framework.
What to Watch Monday
Three numbers matter above all others. First: a dated EBIT margin target, ideally double digits by fiscal 2030. With Nike’s EBIT margin at 8.1% last quarter, a credible path back to at least 10% by fiscal 2030 would confirm the restructuring is working. Second: gross margin guidance that reflects reduced discounting, not just logistics savings. Third: a wholesale revenue growth rate that demonstrates the channel rebuild is durable, not a one-year bounce off a depressed base.
Trading near $38 as of November 13, with a 52-week range of $31.97 to $69.14, the stock has already priced in some optimism. What it has not priced in is certainty. That is Monday’s job.