Why This Stock Now
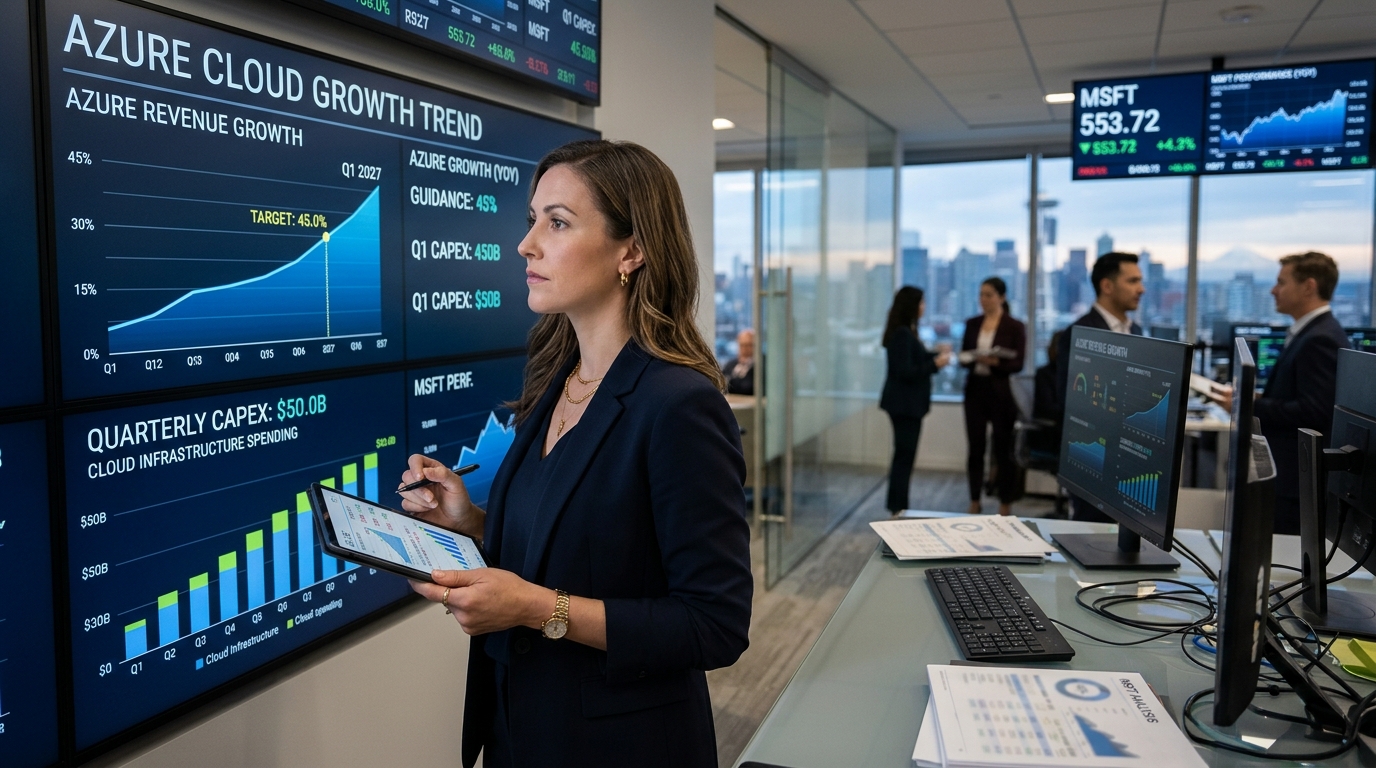
Microsoft (MSFT) has climbed roughly 33% since its last earnings release, and the stock trades about 5.5% below its 52-week high of $553.72 heading into fiscal first-quarter 2027 results Wednesday after the close. That gap is both the opportunity and the complication. Investors are focused on Azure, which grew 43% last quarter and is guided to about 45% in constant currency, and on capital spending set to exceed $50 billion in the quarter. A strong Azure number has room to push MSFT toward new highs. Expectations reset this sharply upward after four consecutive beats, so a miss could retrace weeks of gains overnight.
The Business
Microsoft operates three segments: Productivity and Business Processes, covering Microsoft 365, LinkedIn, and Dynamics; Intelligent Cloud, built around Azure; and More Personal Computing, which houses Windows, Xbox, and Search. The cloud segment is what moves the stock. For the quarter ended March 31, 2026, Microsoft reported revenue of $82.9 billion, up 18% year-over-year, with operating income of $38.4 billion, up 20%. Microsoft said on its fiscal Q3 2026 results call that its AI business surpassed an annual revenue run rate of $37 billion, up 123% year-over-year. Commercial remaining performance obligations increased sharply, rising 99% to $627 billion.
Why Wall Street Is Paying Attention
For the October 28 report, Microsoft’s guidance is for fiscal Q1 2027 revenue of $89.85 billion to $90.95 billion, with Intelligent Cloud revenue guidance of $40.95 billion to $41.25 billion, supported by approximately 45% constant-currency Azure growth. Analyst upgrades from TD Cowen, with a price target raised to $625 from $540, and UBS, raised to $675 from $525, reflect heightened confidence ahead of the October 28 report. Analysts expect Microsoft to post earnings of $4.72 per share on revenue of $90.62 billion, compared with $4.13 per share on $77.67 billion a year ago.
What’s Driving the Opportunity
Microsoft 365 Copilot has reached over 20 million paid seats, with seat adds up 250% year-over-year. By fiscal Q4 2026, Microsoft said it had over 30 million paid Microsoft 365 Copilot seats, adding a second AI revenue line separate from Azure compute demand. The stock trades at a trailing P/E of 31.2. Capital returns remain substantial: Microsoft returned $10.2 billion to shareholders in fiscal Q4 2026 through dividends and buybacks, a figure likely to hold or grow Wednesday.
What Could Go Wrong
The company has guided for approximately $50 billion in capital expenditure this quarter. On its fiscal Q4 2026 earnings call, management also said the shift from finance to operating leases adjusts its calendar-year 2026 capex expectation to approximately $175 billion. Azure is guided to grow 45% in constant currency, setting a demanding benchmark following 43% growth last quarter and a history of sharp share-price reactions to modest disappointments. The PHLX Semiconductor Index has been down about 15% at points this month. Any Azure shortfall on Wednesday could pull MSFT into that rotation away from technology.
The Bottom Line
The prior quarter reset expectations sharply upward: Microsoft earned $4.74 a share against a $4.24 consensus and booked $90.01 billion in revenue versus an $87.62 billion estimate. Wednesday tests whether that track record holds against the highest bar the company has set for itself. Azure at or above 45% growth, combined with capex commentary that frames spending as capacity-filling rather than open-ended escalation, gives MSFT a legitimate path to a new closing high before year-end. That is the case for owning it going into October 28.