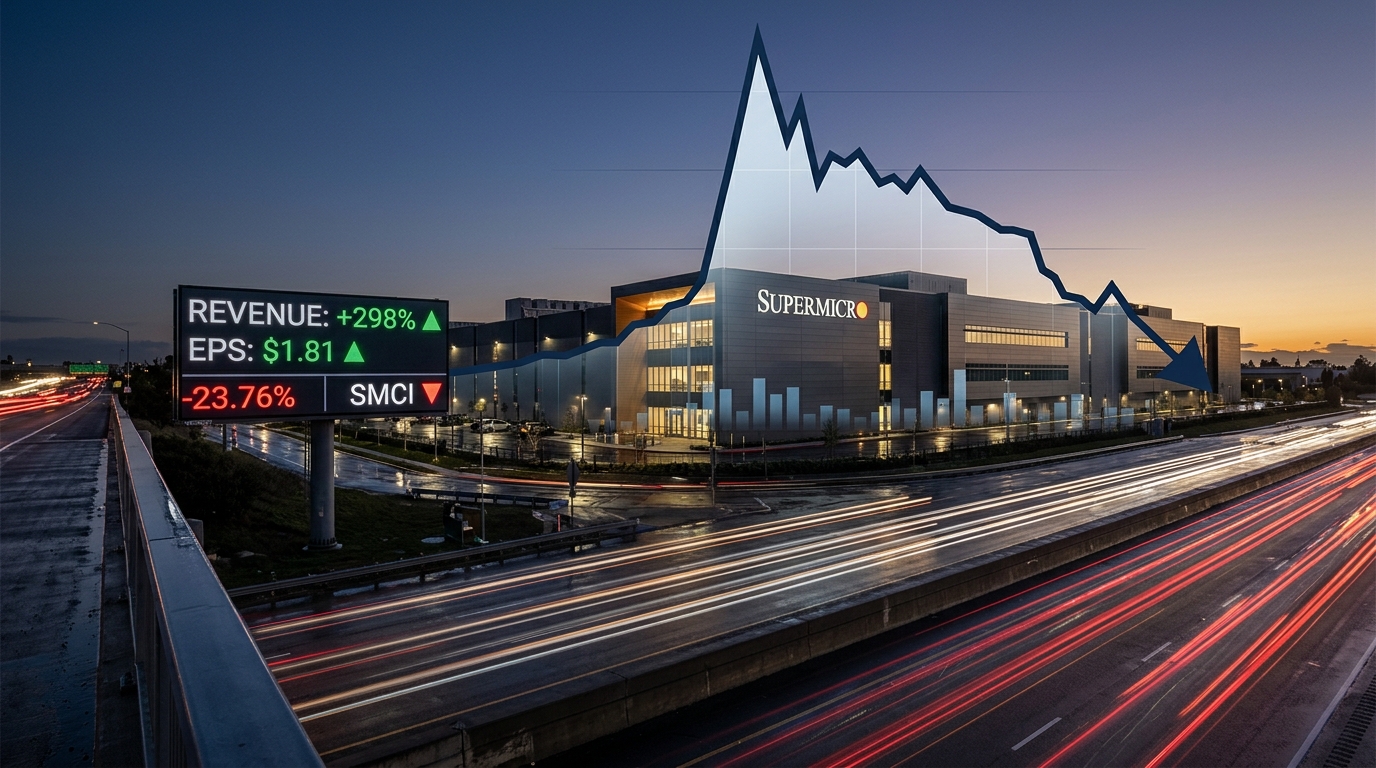
Super Micro Computer reported fiscal first-quarter 2027 earnings on November 3 that should, by any surface reading, have sent the stock higher. Non-GAAP EPS came in at $1.81 against a $1.23 consensus estimate. Revenue rose 298% year over year to $19.9 billion, well above the high end of the company’s own pre-announcement range. The full-year revenue outlook was raised to $72 billion to $82 billion. By Wednesday morning, shares were up more than 8% in premarket trading.
By Thursday, SMCI was trading at $27. Down roughly 31% over one month. The after-hours pop had evaporated completely, and the stock was sitting near a three-month low.
The market is not confused. It is reading the balance sheet.
The Working Capital Problem Underneath the Revenue
Super Micro earned $2.23 billion in GAAP net income for fiscal 2026 and still burned $6.97 billion in free cash flow on $39.1 billion in net sales. That is not a rounding error. It reflects a company whose growth requires an almost continuous injection of working capital that earnings cannot self-fund.
Inventory reached $12.9 billion at fiscal year end, up from $4.7 billion a year earlier. Accounts receivable climbed to $6.1 billion from $2.2 billion. The cash conversion cycle stretched to 113 days. To cover the gap, Super Micro raised about $7.0 billion through equity and equity-linked financing transactions announced in June 2026 and ended fiscal 2026 with approximately $8.7 billion of consolidated indebtedness, alongside $7.52 billion of cash and cash equivalents. Consensus still sees fiscal 2027 free cash flow of roughly negative $1.3 billion.
At $27, the stock trades around 8x trailing earnings. That is cheap only if earnings are the right denominator. When a company this capital-intensive funds growth through debt and dilution rather than its own operations, the earnings figure overstates the cash available to shareholders. The valuation compression is the market pricing that gap.
The Margin and Concentration Signal
The quarter’s other complication landed in a single sentence from new CFO Mark Long on the earnings call. One large data center customer accounted for 44% of Q1 revenue, up from 28% for all of fiscal 2026. At $19.9 billion in quarterly sales, that implies roughly $8.8 billion flowed from one buyer. Some analysts have speculated that SpaceX is the likely account.
Revenue at that concentration is not diversified revenue. It is a supplier relationship. And the margin profile of that relationship is already moving in the wrong direction. GAAP gross margin fell to 12.7% in Q1, a sequential drop of 480 basis points from the 17.5% reported in Q4 fiscal 2026. Management guided full-year gross margin to 11.8% to 12.2%, and acknowledged that the second half will be below the first as large AI deployments shift the product mix further toward lower-margin rack-scale systems.
Gross margin has now declined from 18% in fiscal 2023 to 10.8% for fiscal 2026 as a whole. The company’s explanation, that it is trading margin for market share, is consistent with its behavior. Whether that trade produces durable returns depends entirely on whether the customer base diversifies before the next hardware cycle resets demand.
What to Watch Before Calling It Cheap
The bear case is not that Super Micro is failing. Backlog hit a record even after revenue rose 79% sequentially, and Q2 guidance of $19.5 billion to $21.5 billion sits well above the prior Street estimate. Demand is real.
The case against buying the compressed multiple is structural. Until operating cash flow turns sustainably positive, every quarter of growth requires the company to go back to lenders or equity markets. That funding cost is not visible in the earnings per share line, but it accrues to shareholders through dilution and interest expense. The February earnings report, covering Q2 fiscal 2027, will show whether the working capital cycle is finally tightening or whether $19.9 billion in revenue just means a larger inventory build ahead.
At $27 and roughly 5.6x forward earnings, SMCI offers a real return if the cash conversion cycle normalizes. It offers a painful lesson if it does not.