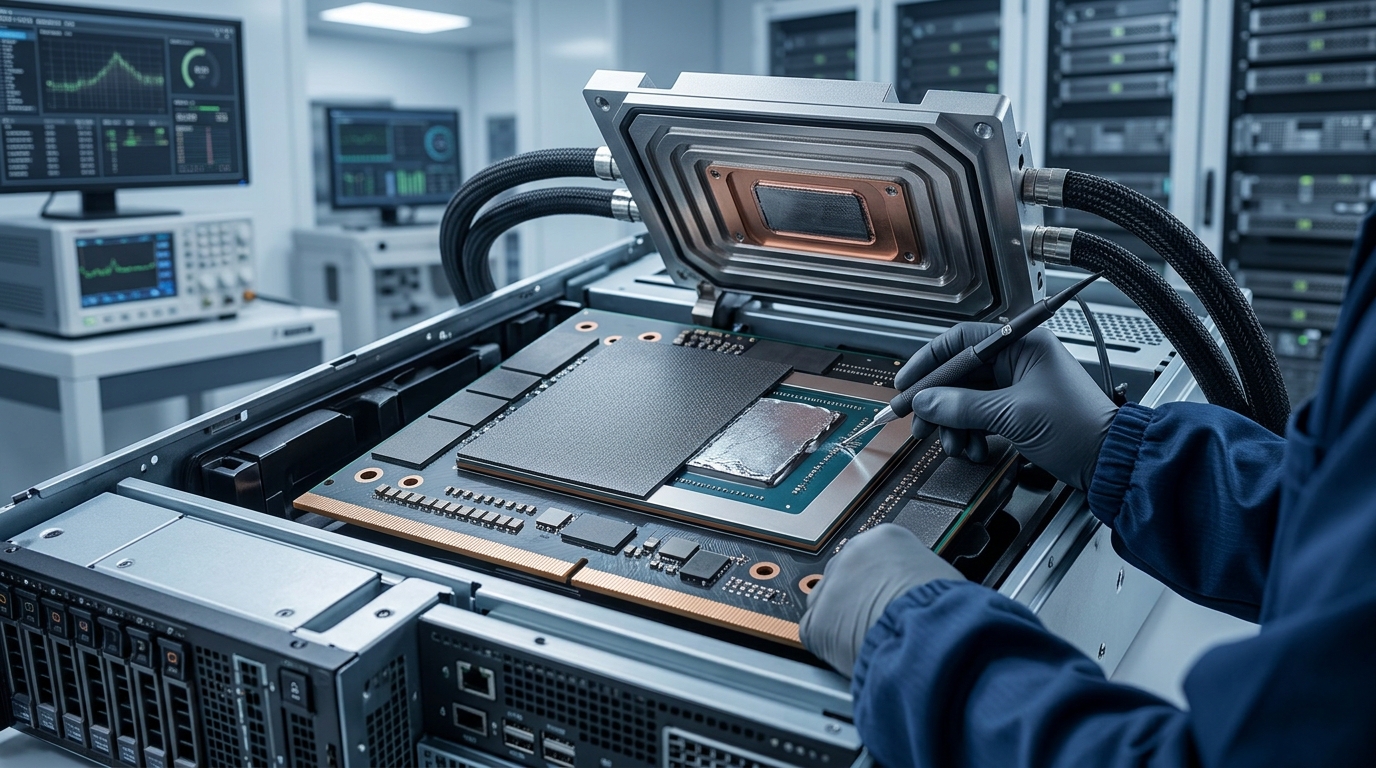
Most of the coverage of Nvidia’s Vera Rubin ramp has focused on rack counts and hyperscaler allocation. The more consequential story is happening at a scale most traders haven’t zoomed into: the roughly 50-to-100-micron layer of material sitting between each GPU die and its cold plate. That layer, the thermal interface material, now determines whether a $100 million training run finishes or throttles to a halt.
In May 2026, Nvidia finalized a decision that reshuffled its supplier relationships. For standard Vera Rubin, running at roughly 1.8 to 2.3 kilowatts per GPU in public supply chain disclosures, the company moved away from an indium-based liquid-metal TIM and toward a graphite pad for volume production. The reasoning was industrial rather than purely thermal: the pad approach offers sufficient performance, higher stability, and more controllable manufacturing at the scale AI factories require.
The pivot matters because Rubin Ultra, the higher-power configuration tied to the Kyber rack roadmap and widely discussed around 600 kilowatts per rack, is still described in some industry reporting as leaning on liquid-metal TIM alongside more advanced cold plate designs such as microchannel architectures. That combination can lower interface resistance versus conventional paste, but it introduces corrosion and materials-compatibility risk that bare copper struggles with. Independent supply chain research has reported Nvidia using a gold-plated cold plate surface at the GPU contact as a corrosion barrier in designs that contemplated liquid metal, even as parts of the stack shifted toward graphite in later qualification.
That engineering constraint feeds directly into a supply chain bottleneck. Nvidia named four cold plate suppliers at GTC in March: Asia Vital Components, Cooler Master, Jentech, and Delta Electronics. Separate supply chain reporting later added BOYD and Auras as key cold plate suppliers for Rubin-class systems, while Jentech has also been described as supplying heat spreaders for the platform. If Auras begins shipping Rubin cold-plate modules in the second half of 2026, it would broaden the qualified supplier set beyond the initial GTC list.
The thermal stakes are not abstract. A single CRAC failure in an air-cooled training cluster can push hot-aisle temperatures sharply higher within minutes, triggering automatic throttling across millions of dollars of compute. At Rubin Ultra densities, targeting 600 kilowatts per rack on the Kyber platform, inadequate thermal interface performance doesn’t slow a job down, it cascades.
For traders, the split between standard Rubin and Rubin Ultra creates two distinct exposure windows. Standard Rubin, entering production in the second half of 2026, benefits graphite-pad and related interface-material suppliers and the cold plate ecosystem that is being standardized for Rubin racks. Rubin Ultra, a 2027-forward platform, concentrates demand in higher-spec liquid cooling hardware and precision cold plate fabrication. Indium Corporation has long marketed liquid-metal TIM alloys to electronics and thermal management markets, and has been flagged by some analysts as a potential beneficiary if liquid metal remains in the high-end TIM stack. Diamond-copper heat spreader materials, used to attack localized hot spots, represent a third layer of supply chain exposure, with domestic Chinese players such as Ruiwei New Materials and Bozhi Jinzuan positioned in diamond-copper composite and diamond-substrate categories.
The core trade: Nvidia’s thermal architecture decision wasn’t a single bet on one material. It was a tiered system where the highest-performance, highest-margin SKU demands the most specialized supply chain. Watch which cold plate and TIM suppliers gain Nvidia qualification status as Rubin Ultra ramps. Those qualification lists tend to be sticky.